Wednesday, August 12, 2015

Mortgage Lending Is NOT Out of Control!!

Mortgage Lending is NOT Out of Control! | Simplifying The Market

Mortgage Lending is NOT Out of Control!!

This year, both Freddie Mac & Fannie Mae have introduced new programs that only require a 3% down payment on a mortgage in order to purchase a home. Earlier this month, the Mortgage Bankers’ Association reported that adjustable-rate mortgages (ARMs) may be making a slow comeback as the share of ARMs increased to 7.4 percent of total mortgage applications. Some see this loosening of lending standards as a point of concern.

We know that the ridiculously low lending standards of the early 2000’s were part of the reason a housing bubble formed and burst last decade. Some are worried that we are headed down the same road that caused that housing crisis.

However, a recent survey of a distinguished panel of over 100 economists, investment strategists, and housing market analysts conducted by Pulsenomics showed the vast majority disagree. The survey revealed that only 4% of the experts felt that over the next twelve months lending standards would “ease too much, become too lax”.

Here are the results of that survey:

Mortgage Access | Simplifying The Market

Bottom Line

There is no question that lending standards are easing; thereby giving more families the opportunity of accomplishing the American Dream of homeownership. However, we are not going back to the ridiculousness of the last decade.

Tuesday, August 11, 2015

Don't Wait to Move Up to Your Dream Home!

Don’t Wait to Move Up to Your Dream Home! | Simplifying The Market

Don’t Wait to Move Up to Your Dream Home!

Sellers should realize that waiting while mortgage rates are increasing probably doesn’t make sense. As rates increase, the price of the house you can afford will decrease if you plan to stay within a certain budget for your monthly housing costs.

Here is a chart detailing this point:

Buyer's Purchasing Power | Simplifying The Market

With each quarter percent increase in interest rate, the value of the home you can afford decreases by 2.5%, (in this example, $10,000). Experts predict that mortgage rates will be closer to 5% by this time next year.
Act now to get the most house for your hard earned money.
 
http://goo.gl/Yld1vs

Monday, August 10, 2015

Where Are Mortgage Rates Headed? This Fall? Next Year?

Where Are Mortgage Rates Headed? This Fall? Next Year? | Simplifying The Market

Where Are Mortgage Rates Headed? This Fall? Next Year?

Below is a chart created using Freddie Mac’s July 2015 U.S. Economic & Housing Marketing Outlook. As you can see interest rates are projected to increase steadily over the course of the next 12 months.

Mortgage Rate Projections | Simplifying The Market

How Will This Impact Your Mortgage Payment?

Depending on the amount of the loan that you secure, a half of a percent (.5%) increase in interest rate can increase your monthly mortgage payment significantly.
Dr. Frank Nothaft, the SVP & Chief Economist for CoreLogic, had this to say in their latest MarketPulse:
“If you are thinking of buying a home and have the financial means to do so, this could be a good time to take a look at the neighborhoods you are interested in. We expect home prices in our national index to be up about 4.3% in the next 12 months, and mortgage rates are also likely to increase over the next year.”
If both the predictions of home price and interest rate increases become reality, families would wind up paying considerably more for their next home.

Bottom Line

Even a small increase in interest rate can impact your family’s wealth. Meet with a local real estate professional to evaluate your ability to purchase your dream home.
 
http://goo.gl/VuOxQU

Friday, August 7, 2015

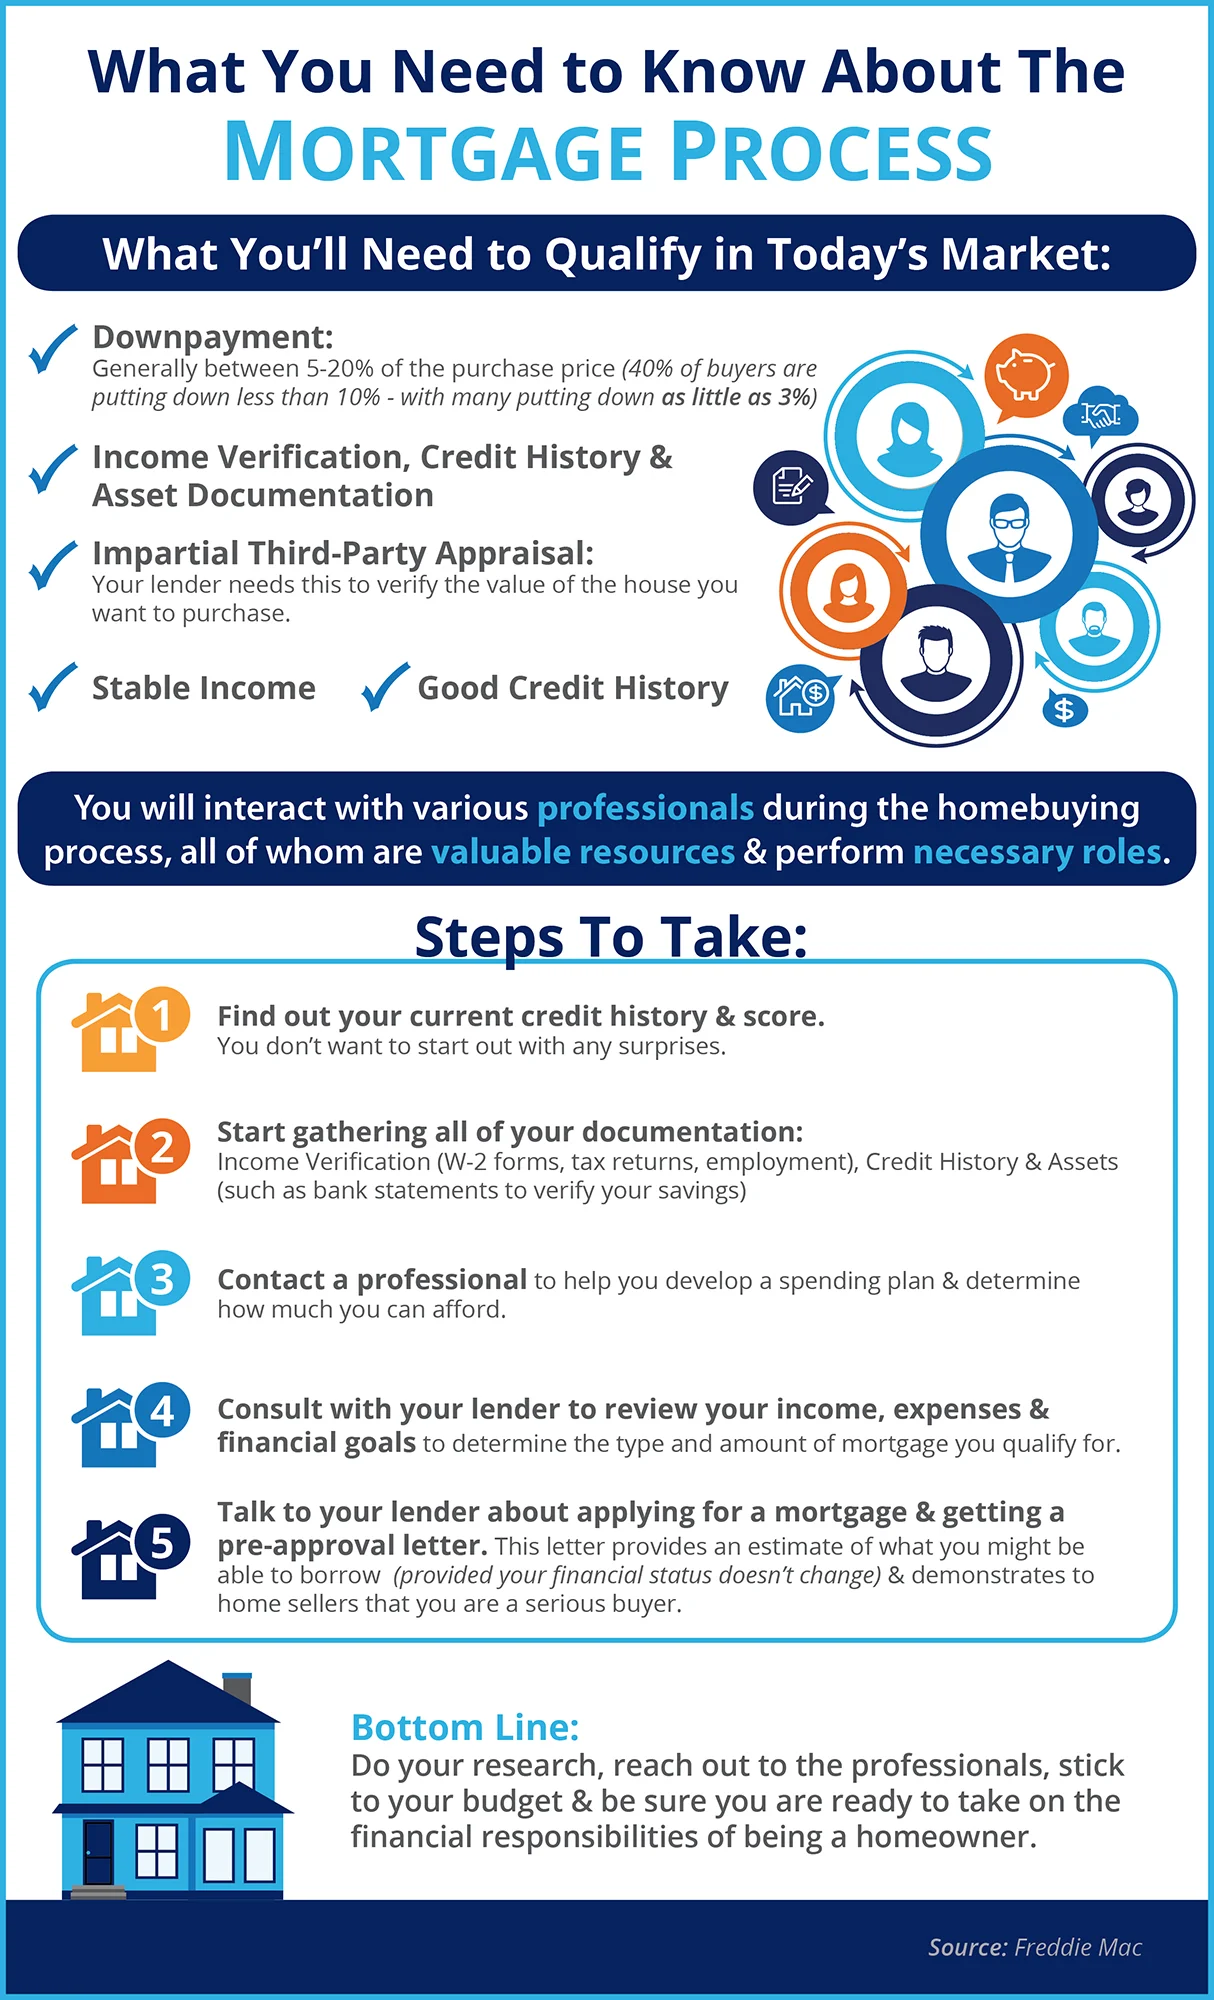
What You Need to Know About the Mortgage Process


What You Need to Know About the Mortgage Process


What You Need to Know About the Mortgage Process | Simplifying The Market

Some Highlights:

  • According to Freddie Mac, 40% of buyers are putting less than 10% down, with many putting down as little as 3%.
  • Have a budget and stick to it!
  • Know your credit score and history!
  • Reach out to a professional who can help you with the process!

http://goo.gl/R8S2hK

Thursday, August 6, 2015

An Easy Way to Find the Perfect Real Estate Agent

An Easy Way to Find the Perfect Real Estate Agent | Simplifying The Market

An Easy Way to Find the Perfect Real Estate Agent


If you are thinking of buying or selling, you need an agent who can help make sense of this rapidly evolving housing market. You need an agent who can help you price your home correctly at the beginning of the selling process. You need an agent who can help you determine what to offer on your dream home without paying too much or offending the seller with a low-ball offer.
Dave Ramsey, the financial guru advises:
“When getting help with money, whether it’s insurance, real estate or investments, you should always look for someone with the heart of a teacher, not the heart of a salesman.”

Hiring an agent who has their finger on the pulse of the market will make your buying/selling experience so much easier.

But, how do you identify which agents truly understand what is happening and will take the time to simply and effectively explain what it means to you and your family?
One simple way is to check out the agent on social media. What are they posting on Facebook and Twitter? Are they using their social media platforms to share relevant, helpful information or are they just posting cherry pie recipes and cartoons? The best agents are committed to educating the consumer so they can feel confident when they are buying or selling a home.
What they are posting online will help you determine which agents meet the criteria that Dave Ramsey suggested you look for: someone with the heart of a teacher!

http://goo.gl/Fj63bF


Wednesday, August 5, 2015

This Is NOT Your Parents’ 3% Down Payment Plan

This Is NOT Your Parents’ 3% Down Payment Plan | Simplifying The Market

This Is NOT Your Parents’ 3% Down Payment Plan

The report went on to explain that today’s underwriting guidelines are nothing like those that existed just prior to the housing meltdown.

“Pre-crisis underwriting allowed layered risk, that is, the combination of multiple features that amplified credit risk. Low down payments often were combined with variable-payment loan structures, property-based underwriting, and questionable appraisals. These risk factors, along with the ‘irrational exuberance’ of some borrowers, led to large losses during the crisis.”

What is layered risk?

In the pre-crisis environment, many mortgage loans incorporated several additional features besides low down payments that multiplied the total risk of the loans such as: variable payment options, underwriting based on the property not the borrower, questionable appraisal processes. Borrower expectations were also overly optimistic at that time.
Freddie Mac highlights the difference between then and now by using a table in the report:

3 Percent Down Then vs. Now | Keeping Current Matters
By removing the “layered risk”, we can be confident that low down payment programs will not impact the market the way mortgage underwriting impacted the market a decade ago. And the report explains:
“Previous research has found that reduced down payments can increase the relative probability of homeownership among some groups by over 25 percent.”

Bottom Line

We believe the report’s conclusion says it all:
“As long as the underwriting

http://goo.gl/50eC4b

Monday, August 3, 2015

Selling Your Home? Price It Right From the Start!

Selling Your Home? Price It Right From the Start! | Simplifying The Market

Selling Your Home? Price It Right From the Start!


There is no “later.”

Sellers sometimes think, “If the home doesn’t sell for this price, I can always lower it later.” However, research proves that homes that experience a listing price reduction sit on the market longer, ultimately selling for less than similar homes.
John Knight, recipient of the University Distinguished Faculty Award from the Eberhardt School of Business at the University of the Pacific, actually did research on the cost (in both time and money) to a seller who priced high at the beginning and then lowered the their price. In his article, Listing Price, Time on Market and Ultimate Selling Price published in Real Estate Economics revealed:
“Homes that underwent a price revision sold for less, and the greater the revision, the lower the selling price. Also, the longer the home remains on the market, the lower its ultimate selling price.”
Additionally, the “I’ll lower the price later” approach can paint a negative image in buyers’ minds. Each time a price reduction occurs, buyers can naturally think, “Something must be wrong with that house.” Then when a buyer does make an offer, they low-ball the price because they see the seller as “highly motivated.” Pricing it right from the start eliminates these challenges.

Don’t build “negotiation room” into the price.

Many sellers say that they want to price their home high in order to have “negotiation room.” But, what this actually does is lower the number of potential buyers that see the house. And we know that limiting demand like this will negatively impact the sales price of the house.
Not sure about this? Think of it this way: when a buyer is looking for a home online (as they are doing more and more often), they put in their desired price range. If your seller is looking to sell their house for $400,000, but lists it at $425,000 to build in “negotiation room,” any potential buyers that search in the $350k-$400k range won’t even know your listing is available, let alone come see it!
One great way to see this is with the chart below. The higher you price your home over its market value, the less potential buyers will actually see your home when searching.
Price & Visibility | Simplifying The Market
A better strategy would be to price it properly from the beginning and bring in multiple offers. This forces these buyers to compete against each other for the “right” to purchase your house.
Look at it this way: if you only receive one offer, you are set up in an adversarial position against the prospective buyer. If, however, you have multiple offers, you have two or more buyers fighting to please you. Which will result in a better selling situation?

The Price is Right

Great pricing comes down to truly understanding the real estate dynamics in your neighborhood. Let's get together to discuss what is happening in the housing market and how it applies to your home.

http://goo.gl/BDMvyF